RIYADH, SAUDI ARABIA- Saudi Arabia is driving a $90 billion hotel and resort development pipeline across the GCC and North Africa, with about 200,000 new rooms planned across the region. Data from hospitality consultancy HVS shows that the new supply would increase the region’s existing hotel room inventory by 27%. Around 88,000 rooms are already under construction, while a further 25,000 are in final planning. More than 55% of the upcoming supply is expected to be delivered between now and 2030.
Saudi Arabia accounts for more than half of planned rooms
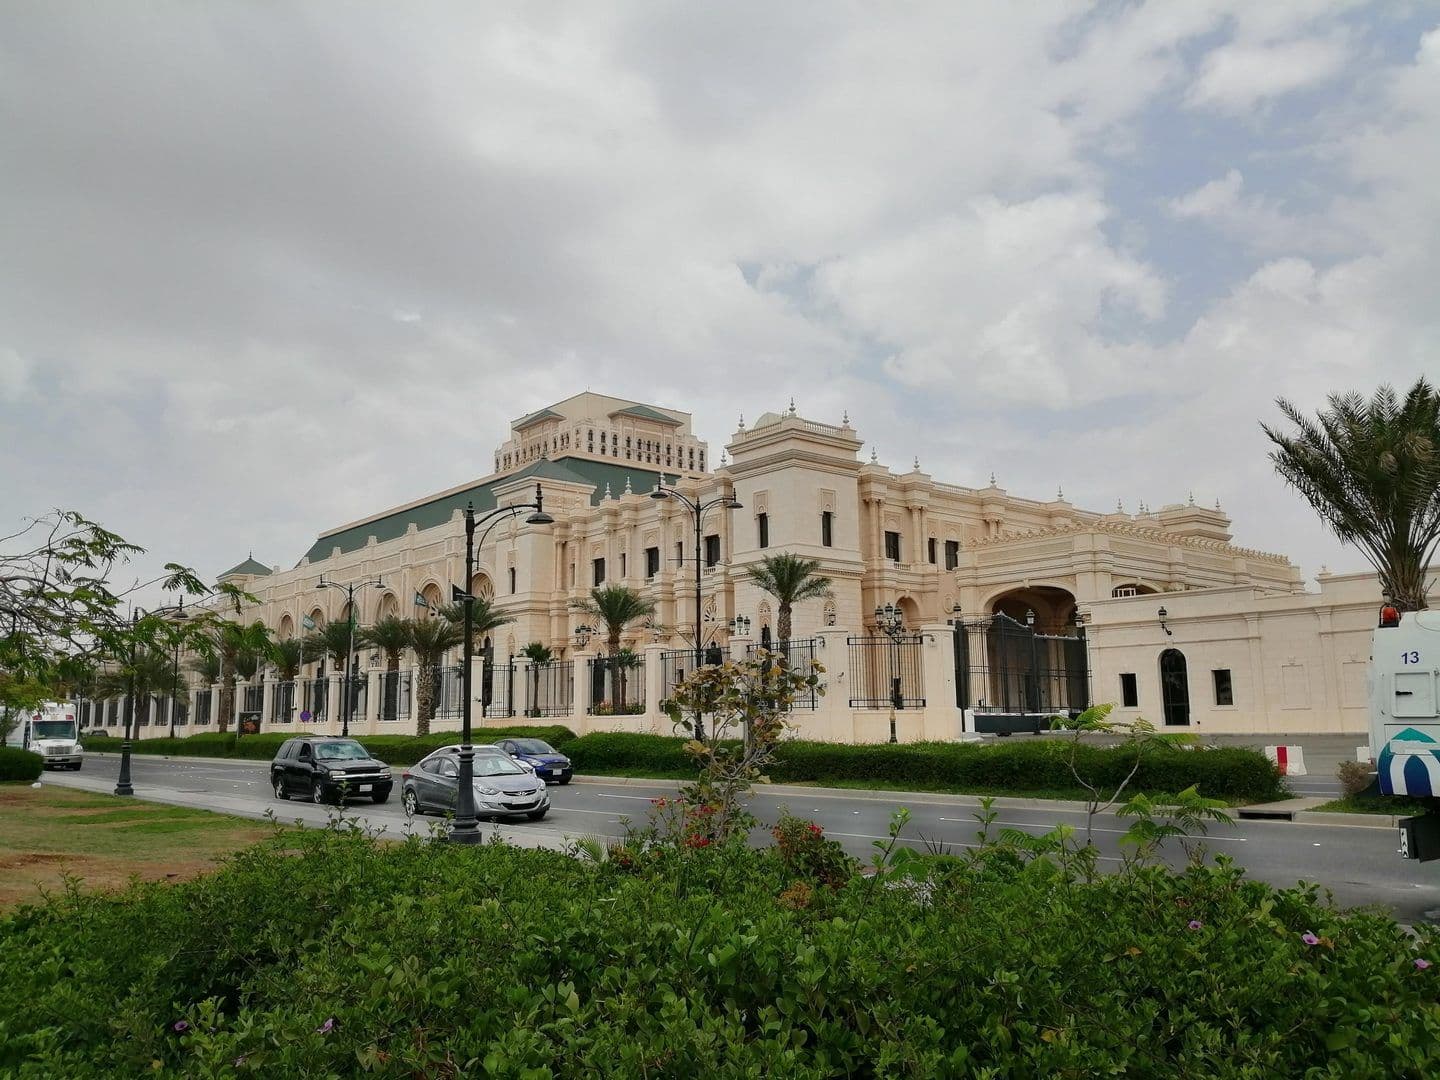
Saudi Arabia has approximately 110,000 rooms under development, giving it the largest share of the regional pipeline. Projects span Riyadh, Makkah, Madinah, Diriyah, NEOM, the Red Sea and AMAALA. Based on HVS's overall estimate of 200,000 rooms, the Saudi pipeline represents roughly 55% of the total by room count.
The expansion is also broadening the types of accommodation being built. Large hotels serving pilgrimage demand are being developed alongside luxury resorts, branded residences and upper-midscale properties.
Luxury and upper-upscale hotels still make up the largest segment of the regional pipeline, but Saudi Arabia is also attracting more mid-market brands. Hampton by Hilton, Holiday Inn Express, Fairfield by Marriott and ibis are among the brands expanding in the Kingdom.
Recent openings show how quickly parts of that pipeline are moving into operation. Red Sea Global opened Four Seasons Resort and Residences AMAALA in June 2026, followed by Rosewood AMAALA in August and Nammos Resort AMAALA in September. At The Red Sea destination, Four Seasons Resort and Residences Red Sea began welcoming guests at Shura Island in May.
Egypt has the region’s second-largest pipeline
Egypt follows Saudi Arabia with around 42,000 rooms planned across Cairo, the North Coast, Red Sea destinations and mixed-use developments.
The UAE remains another major development market, although its hotel sector is more mature. New projects are concentrated around established and emerging destinations in Dubai, Abu Dhabi and Ras Al Khaimah. HVS expects a significant share of the UAE pipeline to be delivered between 2028 and 2030.
The timing is different in Saudi Arabia, where some of the largest destination projects will continue to be delivered in phases into the next decade. Across the full regional pipeline, around 44% of the planned rooms are already under construction.